01
Average days to close
22
From application to closing, the average is 22 days.
22
Financial Planner Dashboard
Your source for mortgage and local real estate news and tools.
Financial Planner Mortgage Calculators
Everything on this page is built for the conversations you have with clients: a weekly market brief, a close-in-a-trust checklist, and ten interactive calculators — after-tax mortgage cost, sell vs. borrow, pay down vs. invest, reverse mortgage vs. HELOC, mortgage payment, refi opportunity, and more. And when you send a client our way, we keep you informed at every step, we never compete for their investments, and we treat your referral like gold.
{referOpen && (Phone or email is required. Provide at least one way to reach the client.
{referContactError &&Enter a client phone number or email so we can reach them.
}Financial planner list
A short email, once a week. It covers how rates moved, plus one planning tip you can use in the next client meeting.
The form is emailed to Questions@The2MG.com. We add you to the financial planner list from there. The brief is a market note, not a quote, rate lock, or offer to lend. Email that same address anytime to be removed.
Process transparency
A referral only works if you can see the process, stay in the loop, know that we know what we're talking about and get your clients to the closing table, without dragging the process out.
How a referred file moves
Average days to close
22
From application to closing, the average is 22 days.
Your point of contact
You work with Ryan or Steve directly. They are Branch Managers and Senior Loan Officers at Luminate Bank, and they stay on the file from the first call through closing.
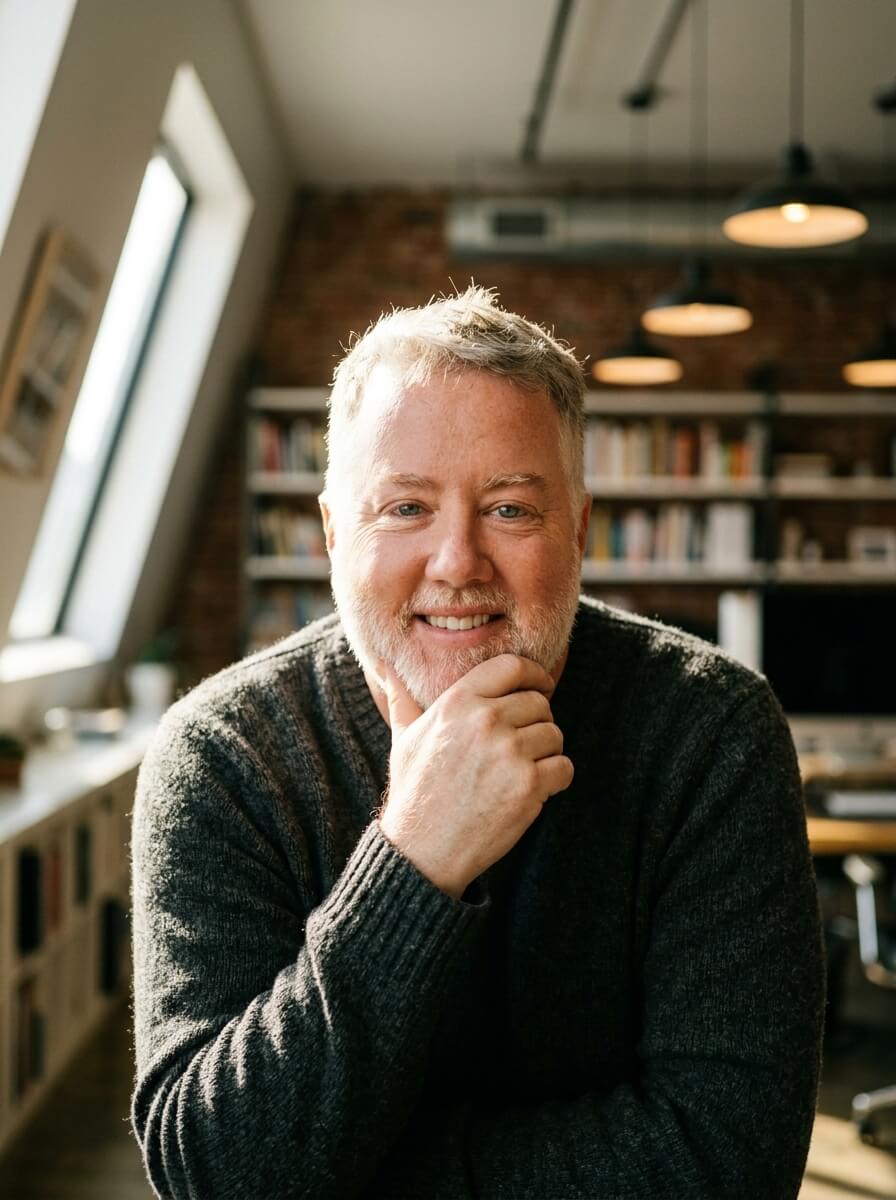
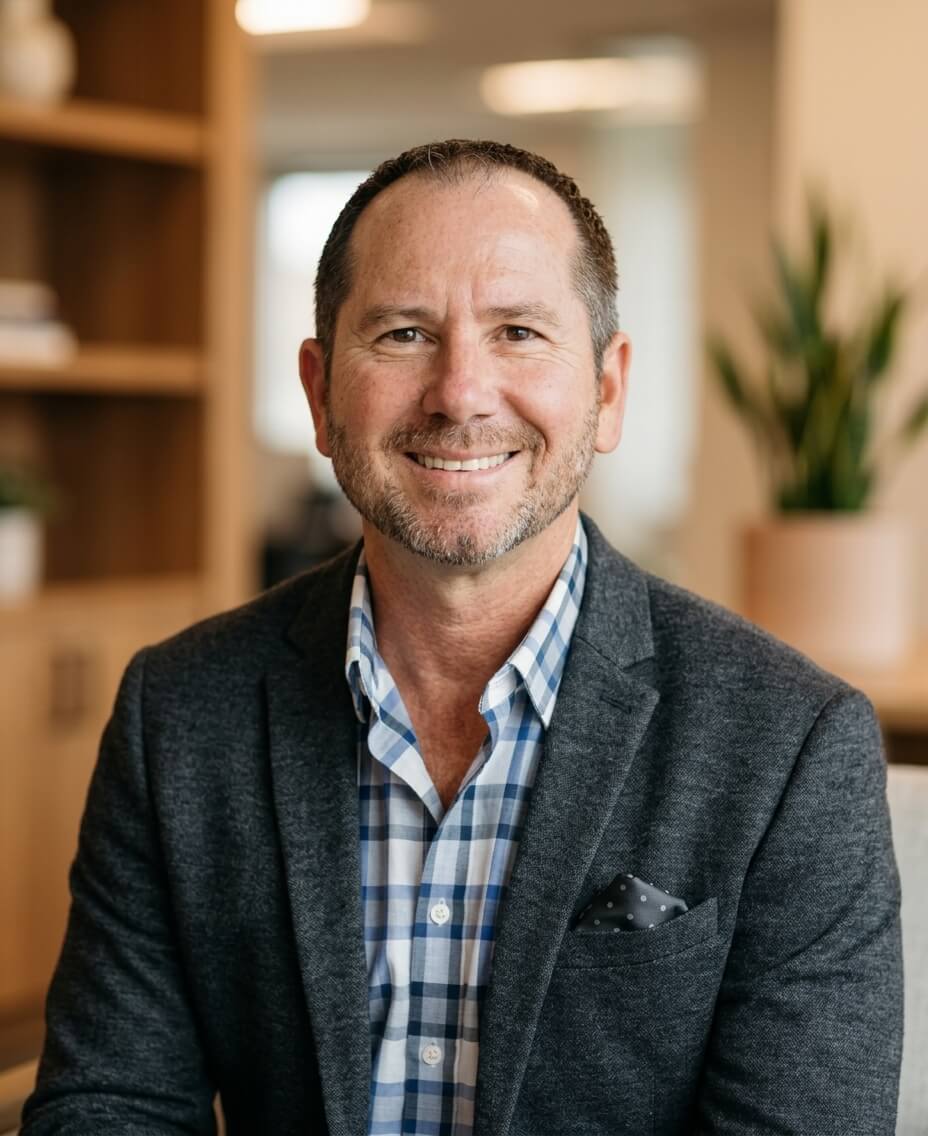
Kept in the loop
When your client authorizes it, we keep you posted as the mortgage moves: where the file stands, what is still needed, and the closing date.
If the client does not give that permission, we do not share their mortgage details. The planning relationship stays with you. We do mortgages only.
22 days is an average, not a promise that every loan closes on that day. Timing depends on the loan program, appraisal, title, underwriting, and how quickly documents come back. All loans are subject to credit and property approval. Sharing file updates with a financial planner requires the client’s permission.
Real-life planning scenarios
These examples show where a mortgage conversation may help a client meet a housing or liquidity goal without automatically turning to an investment sale.
Examples are illustrative only. They are not financial, tax, or legal advice and do not guarantee qualification or a specific outcome.
Planning example
{scenario.body}
For financial planners
These are specific calculators for financial planners, and you are not going to find this set anywhere else. The buttons below open tools for the questions you actually get: selling investments versus borrowing, paying down the mortgage versus investing, reverse mortgage versus HELOC versus selling investments, a refi opportunity checker for savings at three lower rates, refinance breakeven, a DSCR deal analyzer, 15-year versus 30-year with the payment difference invested, a bridge loan cost estimator, a mortgage calculator that shows payment scenarios from the rate, term, and loan amount, and an after-tax cost of mortgage calculator that shows the true borrowing cost after the mortgage interest deduction. Click one and that calculator opens underneath. Opening another calculator closes the one that is open. Each calculator opens blank. Load sample scenario fills in a hypothetical you can see immediately. Those sample rates are illustrative assumptions, not a quote.
See the year-one cost of a fixed mortgage after the mortgage interest deduction, so you can compare borrowing with an after-tax investment return. Results update as you type.
Hypothetical sample. The 7.00% rate and 32% combined bracket are illustrative assumptions, not a quote or an offer from The 2 Mortgage Guys or Luminate Bank. Change any figure, or clear the form to start blank.
Optional. Leave blank for 0%. Added to the federal bracket. That sum is a simplification.
2026 IRS amount for . Changing filing status refills this. Type over it to override.
Everything besides mortgage interest: SALT, charity, and the rest. Leave blank for $0.
Enter the loan amount, interest rate, and federal bracket. The term starts at 30 years. State bracket and other itemized deductions can stay blank.
} {atStarted && afterTax.missing.length > 0 && (Still needed
Check these entries
Effective after-tax interest rate
Stated rate in year one, after the share of interest that is actually deductible.
Monthly principal & interest
Year-1 interest paid
Estimated year-1 tax savings
Effective after-tax monthly cost
Principal and interest minus year-1 tax savings divided by 12.
Lifetime interest vs. lifetime tax savings
interest
tax savings
Gross interest over {atResult.years} years, versus a simple sum of each year’s deductible interest times the combined bracket. The bracket stays constant. Nothing is discounted.
{atResult.takeaway}
Educational estimates only — not tax advice. Tax law is complex and individual; consult a CPA.
For planning comparison only — not a loan quote, offer, or rate lock.
Sell investments vs. borrow
Enter the client’s assumptions and compare the illustrated cost of selling with the illustrated cost of borrowing. The loan rate starts blank. Every assumption stays editable. Illustrative only; not tax or financial advice.
Dollars that would be sold, or borrowed.
Enter 7 for 7%.
Use the combined rate you want to illustrate.
This starts blank. The rate you type is your assumption, not a rate from The 2 Mortgage Guys or Luminate Bank.
Whole years from 1 to 40.
Enter 0 if you want closing costs left out of the illustration.
Enter every assumption to compare the true cost of selling with the true cost of borrowing. Nothing is pre-filled, including the loan rate.
} {assumptionsStarted && sellBorrow.missing.length > 0 && (Still needed
Check these entries
Sell
{sellResult.lower === 'sell' &&Lower illustrated cost
} {sellResult.lower === 'tie' &&Illustrated costs match
}Tax plus growth forfeited
Borrow
{sellResult.lower === 'borrow' &&Lower illustrated cost
} {sellResult.lower === 'tie' &&Illustrated costs match
}Interest plus closing costs
{sellResult.comparison}
{sellResult.breakevenNote}
Cost basis is higher than the amount needed, so taxable gain is zero. This illustration does not apply a tax benefit for the loss.
}Enter every assumption to print a client report.
}Ryan and Steve can walk through the same assumptions for one client. The mortgage stays with us. The planning relationship stays with you.
Illustrative only; not tax or financial advice. Entered rates are assumptions you provide. They are not advertised rates, quotes, rate locks, or offers to lend from The 2 Mortgage Guys or Luminate Bank. Actual tax depends on basis, holding period, filing status, and state tax. Interest may or may not be deductible, and that is not included here. Investment returns are not guaranteed. All loans are subject to credit and property approval.
Pay down the mortgage vs. invest
This is the question planners hear most. Compare an extra monthly principal payment with investing that same amount through the end of the remaining term. The mortgage rate starts blank. Every assumption stays editable. Illustrative only; not tax or financial advice.
Principal still owed. The scheduled payment is principal and interest only.
This starts blank. The rate you type is your assumption, not a rate from The 2 Mortgage Guys or Luminate Bank.
Whole years from 1 to 40.
Principal paid extra each month, or the amount invested instead.
Enter 7 for 7%. Use an after-tax return if you want taxes reflected.
Enter every assumption to compare paying the mortgage down with investing the same extra amount. Nothing is pre-filled, including the mortgage rate.
} {payStarted && paydownInvest.missing.length > 0 && (Still needed
Check these entries
Scheduled principal-and-interest payment: . Both paths use that payment plus every month through {payResult.years} years.
Pay down
{payResult.leader === 'paydown' &&More illustrated wealth
} {payResult.leader === 'tie' &&Ending balances match
}Ending investment balance
Invest
{payResult.leader === 'invest' &&More illustrated wealth
} {payResult.leader === 'tie' &&Ending balances match
}Ending investment balance
Wealth difference
{payResult.comparison}
{payResult.breakevenNote}
Enter every assumption to print a client report.
}Ryan and Steve can walk through the same assumptions for one client. The mortgage stays with us. The planning relationship stays with you.
Illustrative only; not tax or financial advice. The mortgage rate and the investment return are assumptions you provide. They are not advertised rates, quotes, rate locks, or offers to lend from The 2 Mortgage Guys or Luminate Bank. Investment returns are not guaranteed. All loans are subject to credit and property approval.
Reverse mortgage vs. HELOC vs. selling investments
For a client age 62 or older, compare three ways to create monthly cash. See the payment impact, illustrated home equity over time, and what remains for the estate. Every rate starts blank and every assumption stays editable.
Enter planner-supplied figures for one illustration.
Enter every assumption to compare monthly cash flow, home equity, and the ending estate. No rate is pre-filled.
} {rvsStarted && reverseHelocSell.missing.length > 0 && (Still needed
Check these entries
The target is a month for {rvsResult.years} years. “Change vs. today” shows cash received minus a new HELOC payment, with the existing mortgage payment added back only when the reverse path removes it.
Reverse mortgage
{!rvsResult.reverse.feasible ? (Cannot illustrate this path
{rvsResult.reverse.reason}
Ending estate total
{rvsResult.reverse.status}
HELOC
Ending estate total
{rvsResult.heloc.status}
Sell investments
Ending estate total
{rvsResult.selling.status}
| Path | Equity at start | Equity at midpoint | Equity at end | Portfolio at end | Estate total at end |
|---|---|---|---|---|---|
| Reverse mortgage | |||||
| HELOC | |||||
| Sell investments |
These are calculated outcomes under the entered assumptions, not a recommendation. An estate total combines remaining home equity and the remaining portfolio; it does not attempt to value every estate asset or expense.
Enter every assumption to print a client report.
}The amount available for the reverse mortgage is the planner’s figure—not an official principal-limit calculation, a quote, or a rate from The 2 Mortgage Guys or Luminate Bank. Actual reverse-mortgage eligibility, proceeds, counseling, servicing, repayment, and protections follow program rules.
Ryan and Steve can help frame the mortgage assumptions while the investment and estate-planning decisions stay with the client’s advisors.
Illustrative only; not tax or financial advice. Every entered rate and amount is a user-provided assumption—not an advertised rate, quote, rate lock, official reverse-mortgage principal limit, or offer to lend from The 2 Mortgage Guys or Luminate Bank. Property taxes, insurance, and maintenance continue under every path. Investment returns and home appreciation are not guaranteed. All loans are subject to credit, property, program, and borrower approval.
Refi Opportunity Checker
Use this in a trigger-rate follow-up, live in the meeting. Enter the client’s current loan balance, interest rate, and remaining term. The checker shows today’s estimated principal-and-interest payment, then the same balance and term at rates 0.5, 1, and 1.5 percentage points lower.
These figures are illustrative principal-and-interest estimates, not a quote, a rate lock, or an offer to lend. They exclude closing costs, taxes, insurance, and mortgage insurance.
Refinance Breakeven is the detailed next step when you want closing costs, a different term, and the month the refinance pays for itself.
Principal still owed. Greater than $0 and no more than $100,000,000. This starts blank.
This starts blank. Above 1.5% and at most 25%, so each lower rate stays above 0%. The rate you type is your assumption, not a rate from The 2 Mortgage Guys or Luminate Bank.
Whole years from 1 to 40. Each scenario keeps this term.
Enter the current loan balance, interest rate, and remaining term. Nothing is pre-filled. The three lower-rate scenarios appear as soon as those entries are valid.
} {oppStarted && refiOpportunity.missing.length > 0 && (Still needed
Check these entries
Current estimated payment
Principal and interest at with {oppResult.yearLabel} left on .
{oppResult.explanation}
The checker isolates the rate. Refinance Breakeven adds closing costs, lets you change the term, and shows when the new loan costs less. Ryan and Steve can walk through either set of numbers for one client.
Illustrative principal-and-interest estimates only. Not a quote, rate lock, or offer to lend from The 2 Mortgage Guys or Luminate Bank. Closing costs, taxes, insurance, and mortgage insurance are excluded. The balance and remaining term stay the same in every scenario. All loans are subject to credit and property approval.
Refinance breakeven
This is the detailed next step after the Refi Opportunity Checker. Use it when the conversation includes closing costs, a different term, and the break-even timeline. Compare the current loan with a new loan. Both rates start blank. Closing costs are added to the new balance. The result is the first month the refinance costs less, using principal and interest only. Illustrative only; not tax or financial advice.
Principal still owed. Greater than $0 and no more than $100,000,000.
This starts blank. Above 0% and at most 25%.
Whole years from 1 to 40.
This starts blank. The rate you type is your assumption, not a rate from The 2 Mortgage Guys or Luminate Bank.
Whole years from 1 to 40.
Added to the new loan balance. Enter 0 if there are none. The new balance cannot exceed $100,000,000.
Enter every assumption to compare the current loan with the new loan. Nothing is pre-filled, including either rate.
} {refiStarted && refinanceBreakeven.missing.length > 0 && (Still needed
Check these entries
Current loan
{refiResult.fullLeader === 'current' &&Costs less over the full comparison
} {refiResult.fullLeader === 'tie' &&About the same over the full comparison
}Monthly principal and interest
New loan
{refiResult.fullLeader === 'new' &&Costs less over the full comparison
} {refiResult.fullLeader === 'tie' &&About the same over the full comparison
}Monthly principal and interest
Monthly payment difference
{refiResult.paymentText}
Months to break even
{refiResult.breakText}
{refiResult.breakevenText}
{refiResult.explanation}
Enter every assumption to print a client report.
}Ryan and Steve can walk through the same rate-and-term assumptions for one client. The mortgage stays with us. The planning relationship stays with you.
Illustrative only; not tax or financial advice. Entered rates are the planner’s assumptions, not advertised rates, quotes, or offers to lend from The 2 Mortgage Guys or Luminate Bank. This comparison is principal and interest only. Taxes, insurance, and mortgage insurance are not included. All loans are subject to credit and property approval.
Rate-and-Term RefinanceRental purchase
Enter the purchase price, down payment, rate, loan term, gross monthly rent, and monthly expenses. The rate starts blank. The result shows the DSCR ratio, monthly cash flow, and cash-on-cash return. Illustrative only; not tax or financial advice.
Greater than $0 and no more than $100,000,000.
May be $0. Must stay below the purchase price so the loan is above $0.
This starts blank. Above 0% and at most 25%. The rate you type is your assumption, not a rate from The 2 Mortgage Guys or Luminate Bank.
Whole years from 1 to 40.
Used exactly as entered. No vacancy allowance is applied.
Taxes, insurance, HOA, and any other monthly costs other than principal and interest. Enter 0 if there are none.
Enter every assumption to see the DSCR ratio, monthly cash flow, and cash-on-cash return. Nothing is pre-filled, including the rate.
} {dscrStarted && dscrDeal.missing.length > 0 && (Still needed
Check these entries
DSCR
Rent divided by housing cost
Monthly cash flow
Rent minus housing cost
Cash-on-cash
For context
{dscrResult.cashOnCashText}
{dscrResult.explanation}
Enter every assumption to print a client report.
}Ryan and Steve can walk through the same rent, expense, and down-payment assumptions for one client. The mortgage stays with us. The planning relationship stays with you.
Illustrative only; not tax or financial advice. The rate is the planner’s assumption, not an advertised rate, quote, or offer to lend from The 2 Mortgage Guys or Luminate Bank. Rent is used exactly as entered, with no vacancy allowance. All loans are subject to credit and property approval.
DSCR Loans15-year vs. 30-year
Compare total interest on the same loan amount, then see what the monthly payment difference grows to if it is invested. Both rates start blank. The terms stay at 15 years and 30 years. Illustrative only; not tax or financial advice.
Greater than $0 and no more than $100,000,000. Both loans use this amount. Principal and interest only.
This starts blank. Above 0% and at most 25%. The term stays at 15 years.
This starts blank. Above 0% and at most 25%. The term stays at 30 years.
From -50% to 50%. Enter 7 for 7%. Use an after-tax return if you want taxes reflected.
The rates and the investment return are assumptions you type. They are not advertised rates, quotes, or offers to lend.
Enter the loan amount, both rates, and the expected return to compare a 15-year loan with a 30-year loan. Nothing is pre-filled, including the rates.
} {termStarted && termCompare.missing.length > 0 && (Still needed
Check these entries
15-year loan
Monthly principal and interest
30-year loan
Monthly principal and interest
{termResult.paymentText}
{termResult.interestText}
What the difference grows to
The monthly payment difference invested at the end of each month for 30 years. This is also the 30-year path’s ending investment balance.
15-year path
{termResult.leader === 'fifteen' &&More illustrated wealth
} {termResult.leader === 'tie' &&Ending balances match
}Ending investment balance after the full payment is invested from payoff through year 30.
30-year path
{termResult.leader === 'thirty' &&More illustrated wealth
} {termResult.leader === 'tie' &&Ending balances match
}Ending investment balance from investing the payment difference every month for 30 years.
Wealth gap
{termResult.comparison}
{termResult.breakevenNote}
{termResult.comparison}
{termResult.explanation}
Enter every assumption to print a client report.
}Ryan and Steve can walk through the same loan amount, rates, and investment return for one client. The mortgage stays with us. The planning relationship stays with you.
Illustrative only; not tax or financial advice. The rates and the investment return are the planner’s assumptions, not advertised rates, quotes, or offers to lend from The 2 Mortgage Guys or Luminate Bank. Investment returns are not guaranteed. Taxes, insurance, and mortgage insurance are not included. All loans are subject to credit and property approval.
Conventional LoansBridge loan cost
Compare the cost of interest-only bridge financing with the price given up to sell the current home quickly or the premium paid to strengthen a contingent offer. The rate starts blank. Illustrative only; not tax or financial advice.
Bridge financing
Greater than $0 and no more than $100,000,000. Interest is calculated on this amount.
This starts blank. Above 0% and at most 25%. The rate you type is your assumption, not a rate from The 2 Mortgage Guys or Luminate Bank.
A whole number of months from 1 to 36.
$0 or more, and no more than $100,000,000. Added to the financing cost. Not added to the amount used for interest.
Sell first
Greater than $0 and no more than $100,000,000.
From 0% to 50%. Enter 3 for a 3% reduction accepted to sell the current home quickly.
Contingent offer
Greater than $0 and no more than $100,000,000.
The rate, discount, and premium are assumptions you type. They are not advertised terms or offers to lend.
Enter the bridge amount, rate, months outstanding, closing costs, current-home sale price, quick-sale discount, next-home price, and contingent-offer premium. Nothing is pre-filled, including the rate.
} {bridgeStarted && bridgeEstimate.missing.length > 0 && (Still needed
Check these entries
Bridge financing
{bridgeResult.winners.indexOf('bridge') !== -1 &&{bridgeResult.winnerBadge}
}Interest plus closing costs
Principal is repaid separately, usually from the sale of the current home. It is not part of the illustrated cost.
Sell first
{bridgeResult.winners.indexOf('sell') !== -1 &&{bridgeResult.winnerBadge}
}Price hit from a quick sale
Contingent offer
{bridgeResult.winners.indexOf('contingent') !== -1 &&{bridgeResult.winnerBadge}
}Price hit from a stronger offer
Dollar differences
Lowest illustrated cost
{bridgeResult.lowestText}
{bridgeResult.discountNote}
{bridgeResult.premiumNote}
Comparison chart
{bridgeResult.explanation}
Enter every assumption to print a client report.
}Ryan and Steve can walk through the bridge cost, the quick-sale discount, and the contingent-offer premium for one client. The mortgage stays with us. The planning relationship stays with you.
Illustrative only; not tax or financial advice. Entered rates and pricing impacts are planner-provided assumptions, not advertised terms or offers to lend from The 2 Mortgage Guys or Luminate Bank. Principal due at payoff is not a financing cost. Carrying costs, commissions, and changes in home value are not included. All loans are subject to credit and property approval.
Bridge LoansMortgage calculator
Enter a loan amount, rate, and term to see the monthly principal-and-interest payment, then compare that payment across common terms and nearby rates. Tax, insurance, and HOA are optional. The rate starts blank. Illustrative only; not a quote.
Greater than $0 and no more than $100,000,000.
This starts blank. Above 0% and at most 25%. The rate you type is your assumption, not a rate from The 2 Mortgage Guys or Luminate Bank.
Whole years from 1 to 40.
Leave blank for $0. Divided by 12 for the monthly total.
Leave blank for $0. Divided by 12 for the monthly total.
Leave blank for $0. Added as entered. It is not part of the scenario payments.
Enter the loan amount, interest rate, and term to see the monthly payment and nearby scenarios. Tax, insurance, and HOA can stay blank. Nothing is pre-filled, including the rate.
} {mtgStarted && mortgagePayment.missing.length > 0 && (Still needed
Check these entries
Principal and interest
for {mtgResult.yearLabel}
Principal and interest on at .
| Term | Monthly payment | Total interest | Total paid |
|---|
Principal and interest on for {mtgResult.yearLabel}. Rates within 0.50 points of the rate you entered.
| Rate | Monthly payment | Total interest |
|---|
{mtgResult.explanation}
Enter the loan amount, rate, and term to print a client report.
}Ryan and Steve can walk through the same loan amount, rate, and term for one client. The mortgage stays with us. The planning relationship stays with you.
Illustrative only; not tax or financial advice. The rate is the planner’s assumption, not an advertised rate, quote, or offer to lend from The 2 Mortgage Guys or Luminate Bank. Taxes, insurance, and HOA are included in the monthly housing total only when you enter them. Scenario rows are principal and interest only. All loans are subject to credit and property approval.
Loan CalculatorsClose in a trust
Planners hit this on every other file. The client wants the house titled in a trust, and the closing stalls on a missing page, a name that does not match, or a signer who is not the trustee. Use this in the meeting. Check off what you have, then send the packet before a closing date is set.
of {TRUST_CHECK_ITEMS.length} checked
of {items.length}
These are the exceptions. They are not boxes to check off and move on. If one of them is true, call before the client hears a closing date.
{item.body}
))}A starting point for the meeting, not a guideline quote. The trust document and the loan program still have to be reviewed together.
{item.body}
))}Email the full agreement, amendments, vesting, and the attorney’s phone. Ryan and Steve will tell you whether this trust can stay on the file or needs a change before closing.
This checklist is a working aid for a planning meeting. It is not legal, tax, or estate-planning advice, and it is not a promise that a trust will be approved. Trust, title, and loan rules differ by state, program, and investor. All loans are subject to credit and property approval.
Licensed in all 50 states
No matter where your clients are, The 2 Mortgage Guys can help them finance a home. Luminate Bank is licensed to lend in all 50 states.
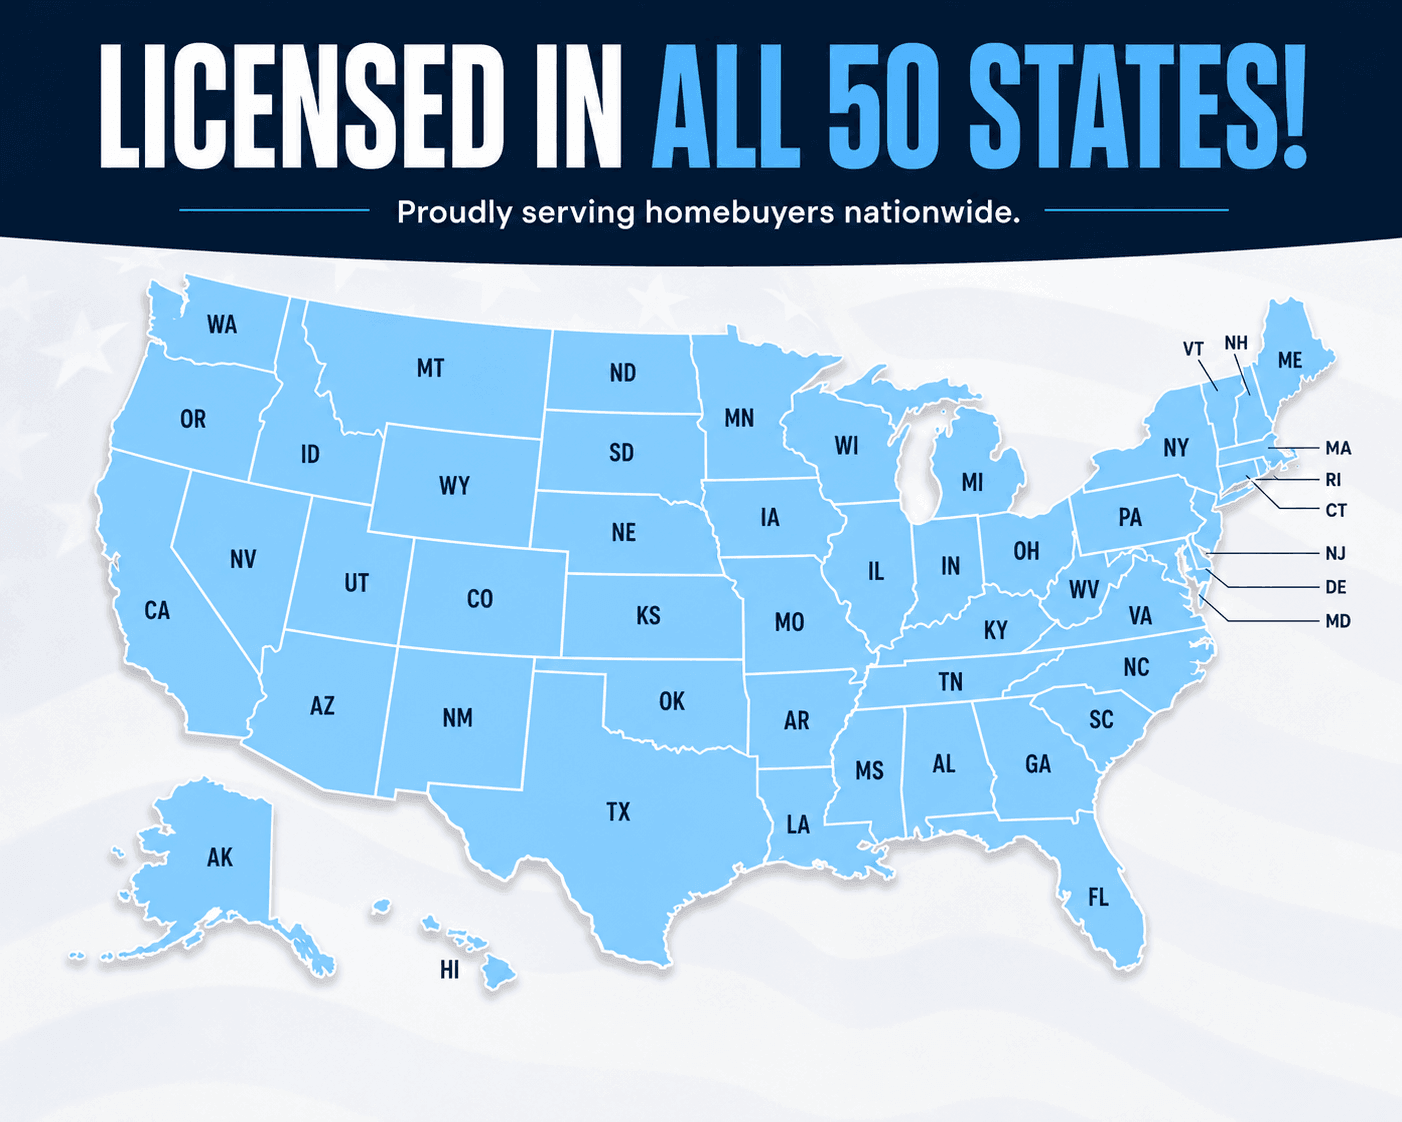
Serving borrowers nationwide
From coast to coast and everywhere in between
Home base: Kokomo, Indiana.
First-time buyers, move-up buyers, and forever homes in any state.
Finance a lake house, beach condo, or mountain retreat anywhere.
Rental properties and DSCR loans in all 50 states.
Corporate transfers, military moves, and cross-state relocations.
One-time close construction loans to build a home anywhere.
Lower a rate, consolidate debt, or tap equity nationwide.
Licensing does not mean every program is offered in every state. All loans are subject to credit and property approval, and product availability can vary.
Property 360
Enter a property address and prepare a branded report with estimated value, nearby sales, and neighborhood context for the next client conversation.
Send a client
Share the goal and the timing. Ryan and Steve are your contacts, and with your client’s permission they keep you posted while the mortgage stays aligned with the plan.
The 2 Mortgage Guys · Ryan Minick & Steve DeLon · Luminate Bank